Global Stock Market Sell-Off: Longest Losing Streak Since 2023
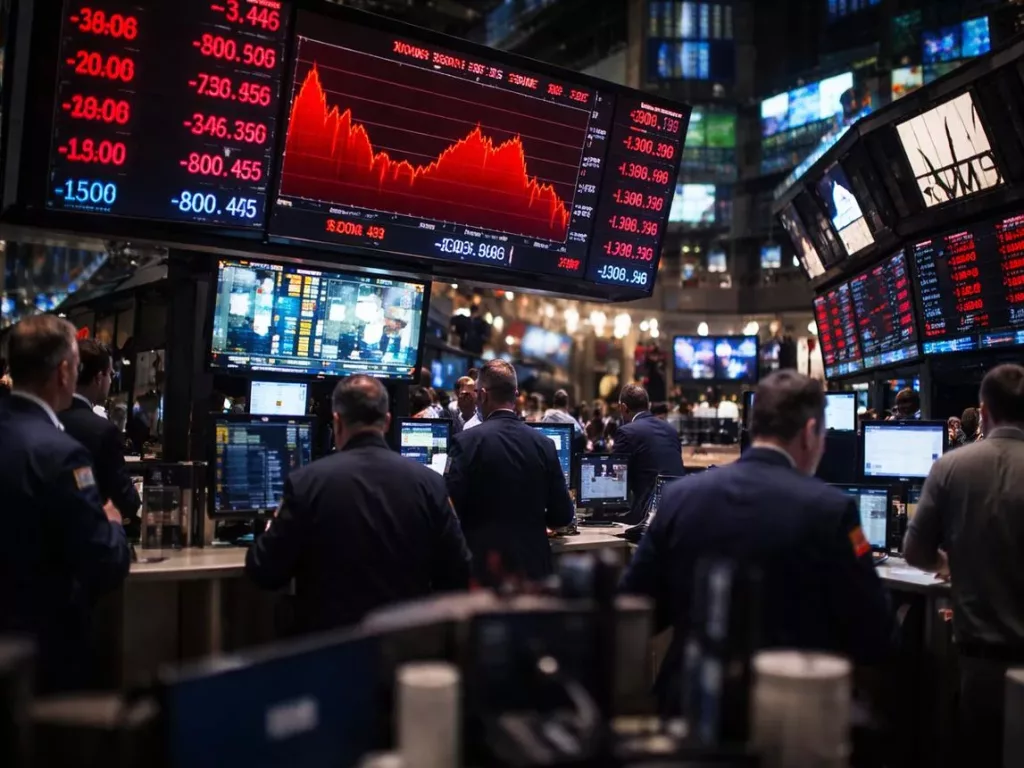
Global equities extend their longest losing streak in three years
Global stock markets came under renewed pressure on Friday, November 20, as investors continued to reduce exposure to technology shares and reassess the financial outlook for the artificial intelligence sector.
The MSCI All Country World Index, which tracks equities across developed and emerging markets, was heading for its seventh consecutive daily decline. That would mark its longest losing streak since September 2023.
The sell-off reflects a change in how investors assess the AI boom. Strong demand for advanced chips and computing capacity is no longer enough to justify high valuations. Market participants increasingly want evidence that the enormous sums committed to AI infrastructure, data centres and model development will translate into sustainable earnings.
The pressure spread well beyond US technology companies. Asian equities recorded particularly sharp losses, European shares weakened, and US futures pointed to further selling after Wall Street’s steep decline on Thursday.
The immediate trigger was not a single corporate announcement. Rather, several concerns converged: uncertainty over returns on AI investment, elevated technology valuations, changing expectations for US monetary policy and a shift towards lower-risk assets.
Key market indicators: November 19–20, 2026
The figures below refer to different market sessions and reporting times. US index closes are for November 19; Asian market figures and European and US futures reflect trading on November 20.
|
Indicator |
Market move |
| MSCI All Country World Index | Heading for 7th consecutive daily decline |
| MSCI Asia Pacific Index | Approximately −3% on Friday |
| MSCI Asia Pacific ex-Japan | Approximately −8.3% for the week |
| STOXX 600 | −1.5% in morning trading |
| S&P 500 | −2.0% on November 19 |
| Dow Jones Industrial Average | −2.2% on November 19 |
| Nasdaq Composite | −2.3% on November 19 |
| Nasdaq 100 futures | Approximately −1.5% on Friday |
The US market closed sharply lower on November 19. The S&P 500 fell 2% to 7,175.83 points, the Dow Jones Industrial Average lost 2.2% to 49,097.06, and the Nasdaq Composite declined 2.3% to 23,879.20.
The breadth of the decline was notable: more than 90% of S&P 500 constituents ended the session lower. The S&P 500 recorded its sixth consecutive daily loss, its longest losing streak since 2024.
The weakness continued across international markets. On Friday morning, the pan-European STOXX 600 was down 1.5%, while Nasdaq 100 futures indicated additional pressure on US technology shares.
These figures should not be read as simultaneous closing prices. They capture different markets at different stages of the trading day.
Why are global stock markets falling? Five factors behind the sell-off
- Investors are questioning the profitability of artificial intelligence
The central issue is the gap between AI investment and the returns that companies can realistically generate.
Technology companies have committed substantial capital to advanced processors, data centres, energy infrastructure and AI model development. These investments are intended to support future growth, but the scale of expenditure has raised questions about how quickly it can be converted into revenue and operating profit.
Investors are increasingly distinguishing between demand for AI technology and the ability of companies across the ecosystem to monetise that demand.
A growing market for computing power does not automatically guarantee attractive returns for every chipmaker, cloud provider or AI developer. The financial outcome depends on pricing, competition, operating costs, capital expenditure and the pace at which customers adopt paid AI services.
This distinction is becoming central to the valuation of technology companies.
- Technology valuations are being reassessed
AI-related stocks benefited from strong investor expectations during the technology rally. Companies associated with semiconductors, cloud computing and data-centre infrastructure attracted capital on the assumption that AI adoption would support a prolonged period of rapid growth.
The current correction suggests that some investors are reconsidering how much future growth is already reflected in share prices.
When valuations depend heavily on earnings expected several years ahead, even a modest deterioration in confidence can have a significant impact. Investors may demand stronger financial evidence before accepting premium multiples.
This does not necessarily mean that the long-term AI opportunity has disappeared. It means that the market is becoming more selective about which companies can turn technological leadership into sustainable cash flow.
- Interest-rate expectations are adding to market uncertainty
Monetary policy remains an important part of the market equation.
Technology and growth companies are particularly sensitive to changes in financing costs and discount rates because a substantial part of their expected value may depend on future earnings. Higher interest rates can reduce the present value of those expected cash flows and make borrowing more expensive.
The latest market moves also reflect changing expectations about the Federal Reserve. Investors are weighing the possibility of a more hawkish policy stance against concerns about economic growth and financial conditions.
There is an important distinction, however: the fall in Treasury yields during the latest risk-off move indicates demand for government bonds. The yield on the benchmark 10-year US Treasury note slipped to approximately 5.02% in the November 20 market snapshot. The bond rally and the broader debate over future Fed policy are related, but they are not the same market signal.
- Competition is challenging established AI leaders
The competitive landscape is changing quickly. Apple’s reported development of its own AI agent has added to questions about the future distribution of AI services and the companies that will capture their economic value.
For investors, the issue is not simply whether another technology company enters the market. It is whether new products and platforms could weaken the pricing power, customer relationships or strategic advantages of existing AI leaders.
The arrival of new competitors can increase development costs and put pressure on margins. It may also shift value from infrastructure providers towards companies controlling consumer platforms, operating systems and distribution channels.
The market is therefore reassessing not only the size of the AI opportunity but also how profits may be divided across the industry.
- Political and geopolitical risks are complicating the outlook
Technology companies are operating in an environment shaped by export restrictions, regulatory scrutiny and geopolitical tensions.
Restrictions on advanced semiconductor exports can affect supply chains, market access and the commercial prospects of chipmakers. Regulatory decisions may also influence how AI products are developed, distributed and monetised.
At the same time, tensions in the Middle East remain relevant to energy prices and broader risk sentiment. Oil prices have fluctuated amid concerns about a possible renewed escalation of the conflict.
These factors do not explain every move in global equities, but they add uncertainty at a time when investors are already questioning the valuations of technology companies.
Where is capital moving during the sell-off?
The latest decline has been accompanied by a shift towards selected defensive assets.
Government bonds attracted demand as investors reduced exposure to equities. The yield on the 10-year US Treasury note moved down to around 5.02%, reflecting the bond market’s risk-off response.
The US dollar remained close to its strongest level since April 2025, supported by safe-haven demand and changing expectations for Federal Reserve policy.
Gold and silver, however, did not follow the same direction. Both metals were under pressure and were heading towards their worst weekly performances since March. This divergence is important: a risk-off environment does not guarantee that every traditionally defensive asset will rise.
Precious metals can also be affected by profit-taking, currency movements, real yields and the need for investors to raise liquidity during periods of market stress.
Oil followed a different pattern. West Texas Intermediate traded near $83 per barrel, while Brent was close to $92. Prices were influenced by geopolitical concerns as well as the broader market environment.
| Asset | Market situation on November 20 |
| US Treasury bonds | Demand increased; 10-year yield around 5.02% |
| US dollar | Near its strongest level since April 2025 |
| Gold | Lower; heading for its weakest week since March |
| Silver | Under pressure; heading for its weakest week since March |
| WTI crude | Around $83 per barrel |
| Brent crude | Around $92 per barrel |
For traders, the key point is that capital rotation is not always a straightforward move from stocks into gold or bonds. Currency, liquidity and positioning can produce different price responses across asset classes.
Asian markets bear the brunt of the technology sell-off
Asia has been among the regions most exposed to the latest decline because several major equity benchmarks have a substantial weighting in technology and semiconductor companies.
The MSCI Asia-Pacific index fell approximately 3% on Friday, while the benchmark tracking Asia-Pacific shares excluding Japan was down around 8.3% for the week. That represented its weakest weekly performance since March 2020.
Japan’s Nikkei 225 fell sharply, with the decline reaching approximately 4.5% in the market snapshot. South Korean and Taiwanese equities also came under heavy pressure, reflecting the importance of semiconductor manufacturers and technology exporters in those markets.
Taiwan was particularly vulnerable because of its exposure to the global semiconductor supply chain. South Korea also faced pressure on its major technology companies, while Japanese technology and investment-related stocks were affected by the broader reduction in risk appetite.
The regional sell-off illustrates how concentrated exposure to one growth theme can amplify market movements. When investors reduce positions in AI-related assets, the impact can spread across countries whose indexes are heavily weighted towards semiconductor and technology businesses.
What does the sell-off mean for global financial markets?
The latest correction points to a change in investor priorities.
During the earlier phase of the AI rally, markets focused on the potential scale of the technology and the expected growth in demand for computing power. Now, the emphasis is shifting towards profitability, financing requirements and the sustainability of business models.
Several consequences are possible:
- Higher volatility in technology shares. Companies with elevated valuations and large future investment commitments may remain particularly sensitive to earnings guidance and changes in investor expectations.
- More selective AI financing. Lenders and investors may scrutinise infrastructure projects more closely, focusing on cash-flow visibility, capital requirements and the expected payback period.
- Pressure on semiconductor and data-centre valuations. Companies supplying AI infrastructure could face greater scrutiny if spending growth slows or expected returns disappoint.
- Uneven demand for defensive assets. Government bonds and the dollar may attract capital, but gold and silver can still fall during periods of forced selling or profit-taking.
- Greater sensitivity to central-bank signals. Inflation data, labour-market reports and Federal Reserve communications may have a stronger influence on equity valuations as investors reassess financing costs.
For market participants, the distinction between a sector correction and a broader bear market remains essential.
What should traders watch next?
The next stage of the market correction will depend on whether selling remains concentrated in technology stocks or spreads into other sectors.
Several indicators deserve attention.
Market breadth. A sustained decline in the number of advancing stocks would suggest that weakness is spreading beyond a narrow group of technology companies.
AI company guidance. Earnings forecasts, capital expenditure plans and disclosures about AI-related revenue will help investors assess whether current valuations are supported by operating performance.
Treasury yields and the US dollar. Their movements will provide clues about changing expectations for monetary policy, liquidity and demand for defensive assets.
Volatility and liquidity. Sharp price movements can widen spreads and increase execution costs. Traders should account for slippage, especially when markets are moving quickly or liquidity is deteriorating. FX24 explains the role of market data and execution in its analysis, Price Feed – The Digital Heart of a Forex Broker.
Asian semiconductor stocks. Their performance may help indicate whether investors are continuing to reduce exposure to the AI supply chain or beginning to distinguish between companies with different earnings prospects.
The direction of the next move will depend less on optimistic statements about AI adoption and more on evidence that investment spending can generate adequate returns.
Conclusion: markets demand proof of AI profitability
The global equity sell-off on November 20, 2026, reflects growing investor caution towards the financial foundations of the AI boom. The MSCI All Country World Index was heading for its seventh consecutive daily decline, while Asian technology-heavy markets recorded particularly sharp losses.
The correction is not, by itself, proof that the AI investment cycle has ended or that a global bear market has begun. US benchmark indexes remained positive for the year after the November 19 session, despite their recent declines.
However, market expectations are changing. Investors are placing greater emphasis on cash flows, financing costs, competitive positioning and the ability of companies to earn a return on substantial AI-related investment.
For traders and investors, the key question is no longer only how quickly artificial intelligence will expand. It is which companies can turn that expansion into sustainable profits – and whether their current valuations already assume too much.
By Claire Whitmore